
Section 269ST of the Income Tax Act, 1961
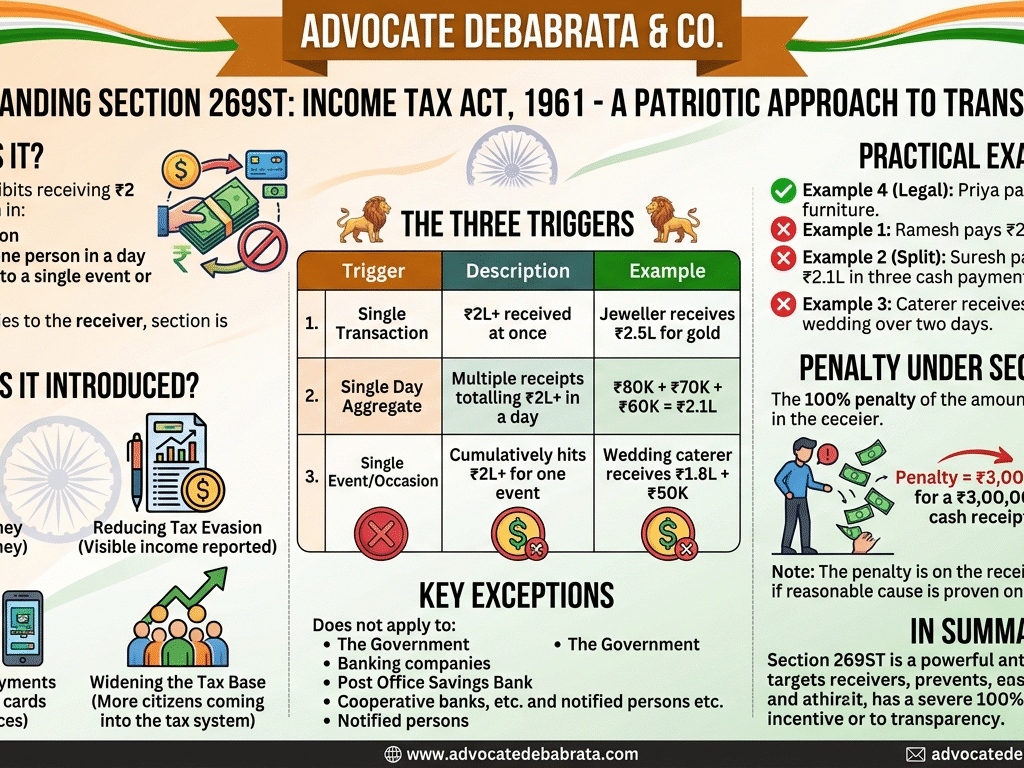
What is it? Section 269ST prohibits any person from receiving ₹2 lakh or more in cash in: The restriction applies to the receiver of cash, not the payer. Why Was It Introduced? The government enacted this provision (effective 1 April 2017) as part of its post-demonetisation drive to formalise the economy. The core objectives were: […]